
Buy your first home in Adelaide!
We cannot wait to bring your homeownership dream to life
Buying your first home is an exciting milestone, but it can feel daunting and overwhelming at times.
That is where we come in!
You can trust our experienced team to support you at every stage of your home-buying journey.
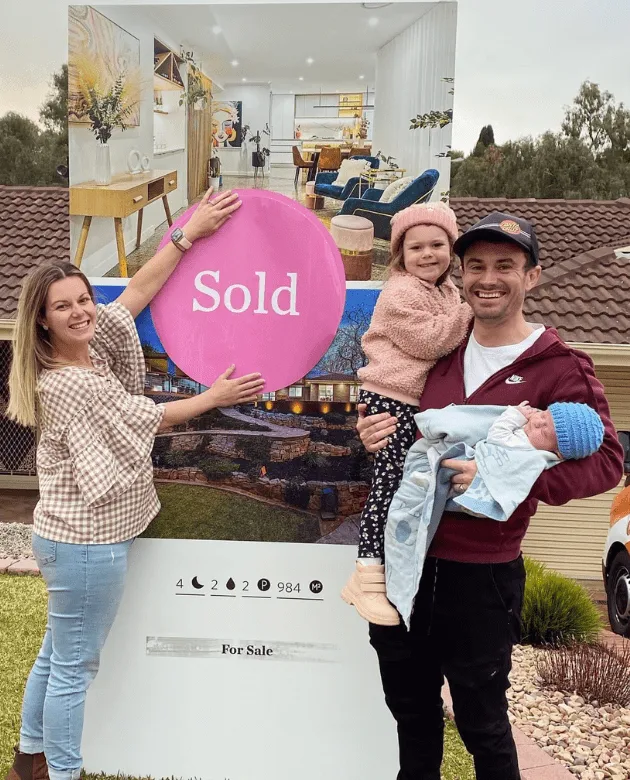
Emily and Rhys
Clients since February 2015

Understand the home-buying process
From assessing your borrowing capacity to settlement, learn how we help you buy a home in Adelaide.

Frequently asked questions
Understand grants, deposits, pre-approval, stamp duty, and much more. No question is too big or small.

Chat to a mortgage broker
Book a fee-free chat with an expert broker to kick-start your journey to becoming a homeowner!

We will hold your hand throughout the entire process to ensure your first home purchase is as smooth as possible!
From helping you find the right home loan or construction loan to overseeing the entire process, our mortgage brokers will coordinate all involved parties to ensure you do not have to worry about a thing.
We do the leg work so you can focus on the fun stuff like choosing the furniture, and, of course, moving in.
Our team will be there to assist you in your negotiations with real estate agents when you find a house you love, introduce you to great experts who can help you with conveyancing and building and pest inspections, and ensure that you are protected against all risks.
Most importantly, we are here to share in your excitement and celebrate the most amazing milestone: your move-in day!

Buying your first home with a mortgage broker
When you work with a Rise High mortgage broker, they will be by your side throughout the entire home-buying process.
They will be your key advisor, and your go-to if you have any questions or concerns.

Discover how much you can borrow to set your price range

Find the right loan for your needs and goals, and get a pre-approval

Find the right property, make an offer and pay your deposit

Get formal approval for your loan and celebrate move in day!

Congratulations! You are now a home owner!

Sit back, relax, and let our team save you money through proactive loan reviews over the life of your loan
Click here for a deeper look into the home-buying process.

Chat with a broker to learn how much you can borrow

Find the right loan for your needs and goals, and get a pre-approval

Choose which property you want to buy, make an offer, and pay your deposit

Get formal approval for your home loan

Celebrate being a homeowner
Sit back, relax, and let our team save you money through proactive loan reviews over the life of your loan
Common questions first home buyers have
When buying your first home, it is natural to have lots of questions. From pre-approval to government grants, here are some things first home buyers have asked our brokers before:
-
Getting started
-
Buying vs building your first home
-
Grants and schemes for first home buyers
-
Finding the right home loan
-
Costs and taxes
-
Ready to Buy?
A lender is a bank, credit union or other financial institution that provides the money you borrow to buy a home. Different lenders have different interest rates, fees, lending criteria and loan features. The right lender will depend on your financial position, deposit, property and the type of loan you need.
An interest rate is the percentage a lender charges you for borrowing money. It affects how much interest you pay on your home loan and the size of your repayments. Interest rates can be fixed for a set period or variable, meaning they can change over time. Even a small difference in rate can make a noticeable difference to the total cost of a home loan.
Your borrowing capacity depends on your income, expenses, existing debts, deposit, credit history and the lender’s assessment criteria. Lenders also test whether you could afford repayments if interest rates were higher. The maximum a lender will offer is not necessarily the amount you should borrow. A mortgage broker can help you understand your borrowing capacity and work out a price range that feels manageable for you.
Usually, you will need some form of deposit or financial support to buy a home. However, options such as a family guarantor may reduce how much you need to contribute yourself. Government programs can also reduce the deposit required for eligible buyers. A genuine no-deposit loan is uncommon and will depend on the lender, your circumstances and the support available to you.
A 20% deposit can help you avoid Lenders Mortgage Insurance (LMI), but you may not need to save that much. Some lenders accept smaller deposits, and eligible buyers may be able to purchase with as little as 5% through the Australian Government 5% Deposit Scheme. Remember to budget for buying costs as well as your deposit.
Pre-approval is an indication from a lender of how much you may be able to borrow, based on their first assessment of your finances. It is not a guarantee of final approval, but we strongly recommend it because it can help you set a realistic property budget and buy with more confidence. Pre-approval generally lasts for a limited period and is particularly useful before making offers or bidding at auction.
There is no single right answer.
A larger deposit can reduce how much you borrow and may help you avoid LMI, but waiting also means continuing to rent and potentially facing changing property prices.
Consider your savings, borrowing capacity, repayment comfort, buying costs and the homes available in your budget. The right timing is when the numbers make sense for you, not simply when you reach a particular deposit size.
Reducing credit cards, personal loans, car loans and other debts can improve your financial position and may increase your borrowing capacity. Lenders consider both your outstanding balances and your ongoing repayment commitments.
However, using all your savings to clear debt may leave you short of a deposit or emergency buffer. It can help to review your debts and borrowing position together before deciding what to repay first.
Debt consolidation combines several debts into one loan. It can make repayments easier to manage and may reduce interest or fees in some circumstances.
However, a lower repayment does not always mean a lower overall cost, particularly if the new loan runs for longer. Turning unsecured debt into debt secured against a home can also increase your risk, so the full costs and structure should be carefully compared.
It can. Lenders review your credit history alongside your income, expenses, debts and overall financial position. Missed repayments, defaults and frequent credit applications may affect how a lender assesses your application. Before applying, you can check your credit report for errors and make sure your existing repayments are up to date.
Start by working out what you can comfortably afford, then identify the features that matter most to you, such as location, space, schools or future flexibility. Research recent comparable sales rather than relying only on advertised prices.
Once you find a property you like, consider the contract, building condition, extra charges and any other checks relevant to the property before committing.
Know your budget before you start negotiating and allow room for costs beyond the purchase price such as stamp duty. Arrange appropriate property inspections, have the contract reviewed by a conveyancer or solicitor and understand your finance conditions. It is also worth keeping an emergency buffer rather than putting every available dollar into the purchase. The goal is to buy a home you can comfortably manage, not one worth the maximum you can borrow.
Family support can take several forms, including a cash gift, a loan between family members or a family guarantee using equity in another property. Each option affects your loan application differently and can carry financial or legal consequences for everyone involved.
If a family member is considering acting as guarantor, they should understand exactly what they are agreeing to and consider independent legal advice.
There is no ideal age to buy your first home.
What matters more is whether you have a suitable deposit, stable enough income, manageable debts and the capacity to meet repayments and other ownership costs. Your plans also matter. Buying may make more sense when you expect to stay in a location for some time and the commitment fits comfortably with the rest of your finances.
Yes, you can choose to make your first property an investment. However, doing so can affect your eligibility for first home buyer grants and schemes, many of which require you to live in the property. It can also affect future eligibility. For example, the First Home Super Saver Scheme generally requires that you have never previously owned property in Australia, including an investment property.
A guarantor home loan involves another person, commonly a parent or close family member, providing a guarantee to support your loan. This may help reduce the deposit you need or avoid LMI in some circumstances.
The guarantor takes on a serious financial obligation and may be responsible for the guaranteed amount if you cannot repay the loan. Both borrower and guarantor should understand the arrangement before proceeding.
Your team may include a mortgage broker, lender, conveyancer or solicitor, and building and pest inspector. Depending on the property and your circumstances, you may also use a buyer’s agent, accountant, financial adviser, quantity surveyor or other specialist. Rise High can help you get the right people involved early so you will understand the finance, contract and property before you make a binding commitment.
Conditional approval means a lender is prepared to consider lending you a certain amount provided specific conditions are met. Final or unconditional approval comes later, once the lender has assessed the property and any outstanding requirements.
Even pre-approved buyers should avoid assuming finance is guaranteed until their lender confirms final approval for the particular purchase.
Buying an established home can give you more certainty about the property, location and purchase price, and you may be able to move in sooner.
Building gives you more control over the finished home but can involve construction timelines, progress payments, variations and additional site costs.
It is important to compare the total cost, location, timing and financial buffer required for each option rather than looking at the advertised price alone.
Most buyers will still need a deposit or another form of acceptable financial contribution. Government support, grants or a family guarantee may reduce the amount of your own savings required, depending on your eligibility and lender.
Building also comes with costs that may not be included in the construction contract, so it is important to understand how much cash you will need before committing.
Yes. First home buyers can purchase vacant land and build later or buy land as part of a house-and-land package. Some first home buyer schemes and state or territory concessions may also apply to eligible land purchases. The rules can include property value limits, construction deadlines and occupancy requirements, so check the requirements that apply where you are buying before signing a contract.
A strong offer is not always the highest offer. Having your finance organised, understanding the property’s market value and being clear about settlement timing can make your offer easier for a seller to consider. A Rise High mortgage broker will help you develop the most attractive offer possible.
Costs can arise from site preparation, soil conditions, retaining walls, utility connections, council requirements, landscaping, fencing, driveways, window coverings and changes to your original selections. You may also need to manage rent or other housing costs while construction is underway. Review exactly what is and is not included in your building contract and keep a financial buffer for costs that change along the way.
If you are borrowing to fund construction, you will generally use a construction loan. Instead of receiving the full loan amount at settlement, funds are usually released to the builder in stages as construction progresses. Interest is generally charged on the amount drawn at that point. Once construction is complete, the loan usually moves into a standard home loan repayment structure.
It depends on where you live, the property you are buying and your personal circumstances.
First home buyer grants and stamp duty concessions are generally administered by state and territory governments, so eligibility, property limits and occupancy requirements differ across Australia.
Federal schemes also have their own rules. Your broker can help you check the relevant government criteria
The First Home Super Saver Scheme allows eligible first home buyers to save through voluntary super contributions and later withdraw eligible amounts towards a home. You can contribute up to $15,000 of eligible voluntary contributions per financial year towards the scheme, up to $50,000 in total per person, subject to the rules. You must follow the ATO’s determination and release process carefully before buying.
The Australian Government 5% Deposit Scheme helps eligible buyers purchase with a smaller deposit without paying LMI. Eligible first home buyers may be able to buy with a deposit from 5%, while eligible single parents or legal guardians may qualify from 2%.
From 1 October 2025, the expanded scheme has no income caps and unlimited places, although property price caps and lender requirements still apply.
Help to Buy is a shared equity scheme where the Australian Government contributes up to 30% of the purchase price of an existing home or 40% of a new home.
Eligible buyers need at least a 2% deposit and must meet income, property price and other requirements. Because the Government owns an equity share, it is different from a standard home loan or deposit guarantee.
Sometimes. Certain federal schemes, state grants and stamp duty concessions can be used together, but each has its own eligibility rules. The combination available to you will depend on where you buy, the property, your circumstances and the scheme requirements at the time. Check eligibility for each program before relying on several forms of assistance in your budget.
Your family might provide a financial gift, lend you money or act as a guarantor. The right structure depends on your circumstances and the lender’s requirements. Gifts and family loans can be treated differently when your application is assessed. A guarantee also creates a significant obligation for the guarantor, so everyone involved should understand the financial and legal consequences before proceeding.
Start with your situation rather than a particular lender or advertised rate. Consider how much you need to borrow, your deposit, repayment comfort and how you expect to use the loan. Then compare suitable loans on interest rate, fees, features and flexibility. A Rise High mortgage broker can compare options from the 70+ lenders we work with and explain how different loan structures may affect you over time.
Useful features can include an offset account, redraw, extra repayments, loan splitting or the ability to change repayment frequency. You may not need every feature, and some can come with higher rates or fees. Think about how you manage your money and what flexibility you are likely to use. Offset and redraw, for example, can reduce interest in similar ways but work differently.
A fixed-rate loan locks in your interest rate for an agreed period, giving you more certainty about repayments during that time. A variable-rate loan can move up or down as the lender changes its rates.
Variable loans often provide greater flexibility, while fixed loans can have restrictions or break costs. Some borrowers split their loan between fixed and variable portions rather than choosing only one.
Home loan repayments are the regular amounts you pay your lender after borrowing money to buy your property. They may be weekly, fortnightly or monthly, depending on your loan.
For most standard home loans, repayments begin shortly after settlement. Construction loans work differently because funds are released progressively and repayments during construction may initially be based on the amount already drawn.
A broker can compare your rate with similar loans available for borrowers in a similar position.
They will also consider fees, loan features, your deposit, loan-to-value ratio and whether the rate is fixed or variable, as these all matter.
Even relatively small rate differences can add up over a long loan term, so a broker will review your loan periodically rather than assuming your current rate remains competitive.
Stamp duty, also called transfer duty in some states, is a state or territory tax that can apply when property changes ownership. The amount depends on factors including where you buy and the property’s value.
First home buyers may qualify for an exemption or concession, but the thresholds and rules differ between states and territories. Check your eligibility with a broker before calculating how much cash you will need at settlement.
LMI is insurance that protects the lender, not the borrower, if a home loan cannot be repaid. It is commonly required when you borrow a high proportion of the property’s value, often when your deposit is below 20%. The cost varies depending on the loan and deposit. Some eligible buyers can avoid LMI through the Australian Government 5% Deposit Scheme.
Yes. First home buyers can purchase at auction, but preparation is especially important because auction sales generally do not have a cooling-off period and the contract is usually unconditional once you are the successful bidder.
Have your finance position, contract review and property inspections sorted beforehand, and decide your maximum bid before auction day.
At an auction, buyers bid publicly and the highest bidder may purchase the property once the reserve is met. The successful bidder generally signs the contract and pays the deposit immediately, without a cooling-off period.
With a private sale, buyers submit offers directly to the seller, usually with more scope to negotiate price, settlement terms and conditions. Rules vary between states and territories.
There is no fixed amount that suits everyone, but it can be helpful to keep some savings available rather than using every dollar for your deposit and purchase costs.
Home ownership can bring unexpected repairs, insurance excesses and changes to regular expenses. When setting your buying budget, consider what cash buffer would help you manage an unexpected cost without relying immediately on credit.
Our clients love us
as much as we love them

"They're all magicians!"
I think this is my 13th loan arranged through Rise High (it could be more). The team has always put my goals first and explored every lender policy to ensure that I'm not just able to achieve my objectives, but to get a great deal more than I ever thought possible. No wonder Rise High takes out just about every top award, every year. They're all magicians! There is simply no more nightmare of uncertainty, and their ethics is unparalleled. From 26 year of personal history in the property market, I couldn't offer any broker a higher commendation!
Nick Hart
Client since 2012

"These guys are faultless!"
These guys are life changers - honest, warm and they get results! Thankyou James & Team for making this a perfect experience for us - we can't recommend you highly enough!
Claudine Innes
Client since 2019

"Highly recommended!!"
RHFS helped us when we decided to buy our first house, and recently with refinancing our home loan. Thuy and Isabella did an amazing work and just leaving us to make the decision with a lot of useful information. Thanks for everything you have done for us, Thuy and Isabella and, of course, Rise High Financial Solutions.
Ceci Mantilla
Client since 2019

"Always on the ball"
We are long-term clients of Rise High and would highly recommend them. Over the years, James and his team have always been helpful and efficient. Karyn has helped us with our most recent loan and she has been fantastic. The team has always been able to work to our needs and timelines, they’re always willing to help, always on the ball and have a great can-do attitude.
Ly Nguyen
Client since 2018

"Very Pleased!"
A HUGE thank you to Nhi & Bryan on the Rise High Financial Team, for their fantastic work. My husband and I have been engaging Thuy and her wonderful team since purchasing our first home back in (2011). Nhi & Bryan, we cannot thank you enough for all your staunch effort, fantastic communication and positive customer service in helping us secure our first investment property. Very Pleased! Thank you.
Phoebe Kavanagh
Client since 2013

"Expertise and professionalism"
Our experience with Rise High was amazing. The process ended up being so much simpler than we had thought thanks to their hard work. The expertise and professionalism they showed meant that it was one less thing for us to worry about. We were kept updated all the way and we're so happy to now be in our new home. We would highly recommend Rise High for anyone looking for these services.
Daniel Goldsworthy
Client since 2021

"have your interests at heart"
James and the team at Rise High were amazing. This was my first time getting a home loan, whereas for my partner has gone through the process with Rise High several times. I must admit I was a little nervous and heard of many bad experiences with other companies but this was certainly not the case. It was so easy, the team led us through the documents they needed and answered all my questions quickly, the whole process was absolutely seamless. James provided us with the best options so quickly and within 10 days we had approval. Pretty unheard of in this market at the moment, just goes to show with the right team anything is achievable. I would highly recommend Rise High to anyone who is looking for a mortgage broker who is trustworthy, reliable and who have your interests at heart.
Rachel Kim
Client since 2022

"got me the best loan I am eligible for"
I had a great experience with Rise High Morgage Brokers. They saved me a lot on my loan and I am confident they got me the best loan I am eligible for. They communicated with me every step of the way and made the process really easy. Thank you
David Gill
Client since 2021

"No question is too complex"
The Rise High team are absolutely on point with everything. Their communication is 11/10. I've refinanced with them twice now and on to my 3rd loan. Each time I have been informed of every step along the way and kept in the loop with everything. No question is too complex. I've referred family and friends to Rise High and will continue to use them in the future!
Georgie Feronas
Client since 2018

"Knocked this one clean out of the park"
I can't rate Rise High Financial Solutions highly enough. When dealing with banks and conveyancers and navigating the sometimes convoluted pathways to property ownership it's important to have expert advice and motivated staff in the form of the team at Rise High 'batting for you'. Thank you so much, you knocked this one clean out of the park. Rob 😊
Rob Allen
Client since 2007
Ready to get started?
Our award-winning mortgage brokers are always here to look after you and support you in achieving your dreams and goals. With a fee-free service, complimentary loan reviews that save you money, and regular updates and communications, you can trust that we will always put you first and have your back!